 Micah
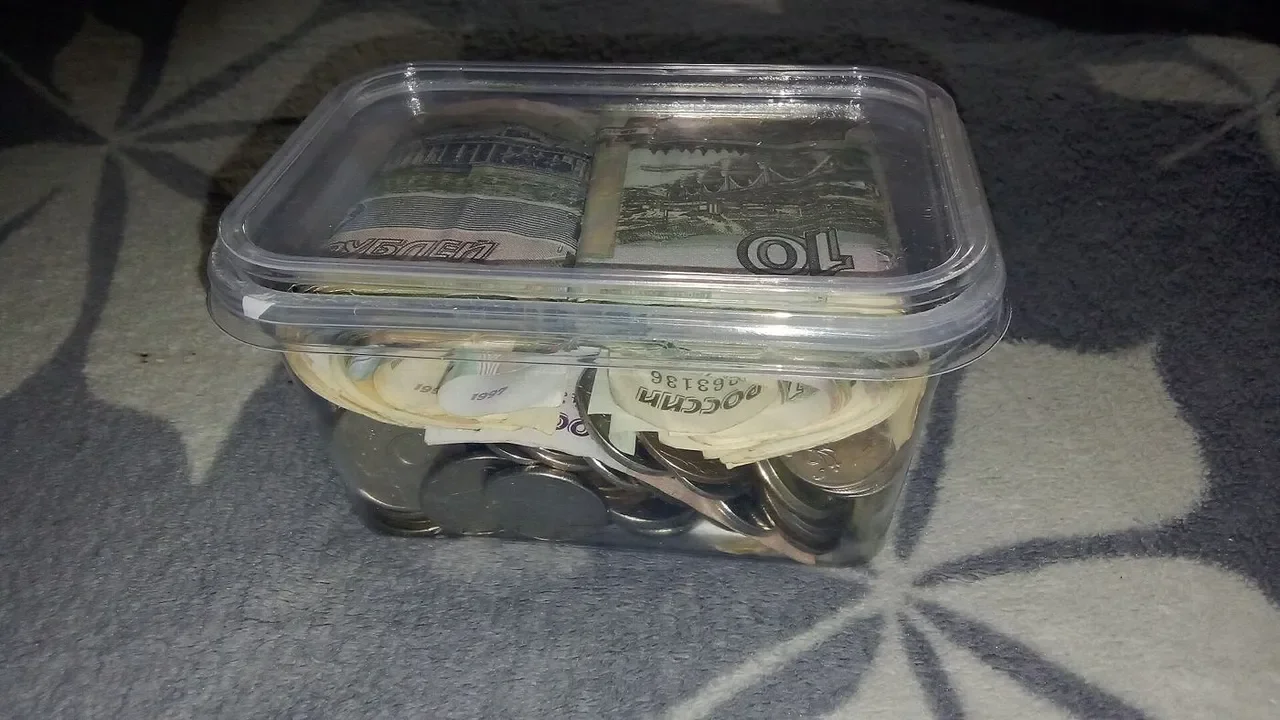
Building an emergency fund can feel overwhelming when the target is several months of living expenses. Financial educators note that small, automatic weekly transfers are helping households make steady progress without waiting to accumulate a large spare sum. Starting with an amount that fits comfortably, then increasing it following a pay rise or a bill reduction, turns saving into a reliable routine habit. The first major milestone is simply covering one unexpected essential repair. Observers note that this encouraging pattern is becoming much clearer as more real world examples are documented and compared carefully over time.
What the Evidence Shows
Keeping emergency money in a separate, easily accessible account reduces the temptation to spend those funds on everyday purchases. Households are advised to review direct debits, note subscription renewal dates, and direct any financial windfalls or cancelled recurring charges straight toward the fund until it reaches a comfortable level. The right target varies depending on individual job security and dependants. What matters most is maintaining a clear purpose, making steady contributions, and resisting risky investments for money that might be needed quickly. Taken together, these steps point toward practical progress that can be measured, shared, and improved by others facing similar challenges. Reporting and analysis from international institutions like the World Bank track these exact developments, and specialists following weekly emergency savings report that the direction remains consistent across independent lines of evidence. One easy source of spare cash is a subscription audit, as households start cancelling services they no longer use.
The Wider Context
For households and small firms, weekly emergency savings matters through tangible prices and access rather than through abstract market commentary. Changes at this practical level usually arrive as an interest rate on an offer letter, a fee on a monthly statement, or a product that quietly disappears from a comparison table. Consumer advocacy groups argue that clear transparency at exactly that point of financial decision is worth far more than any amount of high-level market reporting.
What Happens Next
The outlook for weekly emergency savings hinges on various economic policy choices that will unfold in the open over the coming quarters. Market participants are currently positioned for more than one potential outcome, which explains why the immediate public reaction to each policy announcement has been smaller than the commentary surrounding it. For ordinary savers and borrowers, the core advice remains consistent: review your own personal financial position rather than reacting to the daily headlines.
It is also worth remembering how quickly the economic picture in this area has changed before. Positions that looked entirely settled a few years ago have had to be revised as fresh data arrived, and that same humility is appropriate now. The strongest coverage of this subject, and the most useful guidance, tends to come from sources that update their views openly when the facts shift, rather than defending an earlier stance long after it has stopped fitting the available evidence.
None of this will be settled by a single official announcement, study, or product launch. The primary pattern to watch is gradual accumulation: independent confirmations, honest reporting of setbacks, and steady improvement in the underlying numbers. Readers who follow those reliable signals, rather than the loudest claim of the week, will understand this subject better than the surrounding commentary suggests is possible.